Are Closing Gifts for Real Estate Clients Tax Deductible? The $25 IRS Rule Explained
Real estate agents can deduct client closing gifts, but the IRS caps it at $25 per person, per year. Here's exactly what counts — and what doesn't.
Quick answer
Yes, closing gifts for real estate clients are generally deductible as a business expense — but the IRS caps the deduction at $25 per recipient, per tax year, no matter what you actually spent. That limit comes from IRS Publication 463 and applies to business gifts given directly or indirectly to any one person. Some costs, like engraving or gift wrapping, don't count against the $25 limit if they don't add real value to the gift itself. Spend $150 on a closing gift, and you can still only deduct $25 of it.
Why This Trips Up Real Estate Agents Specifically
Closing gifts are close to a professional norm in real estate. Whether it's a bottle of wine, a personalized cutting board, a gift card, or something bigger for a big-production year, most agents budget for them without ever checking how the IRS treats the expense.
The problem is that "ordinary and necessary" — the general standard for deducting a business expense under Schedule C — doesn't automatically mean "fully deductible." Business gifts are one of the specific categories where the tax code puts a hard ceiling on the deduction regardless of what you actually spent, similar to how meals are capped at 50% in most cases. Gifts are different: it's not a percentage, it's a flat dollar cap per person, per year.
That distinction matters because if you're tracking $200 in closing gifts across four transactions in one deal, or you gave the same referral partner three separate gifts in a year, the deduction math isn't as simple as adding up receipts.
The IRS $25 Limit on Business Gifts, Explained
According to the IRS, you deduct no more than $25 of the cost of business gifts you give directly or indirectly to each person during your tax year. That's a per-person, per-year limit — not a per-gift limit and not a total spending limit for your business.
A few things follow from that:
- It's cumulative per recipient. If you give the same client two gifts in the same year — say, a small gift at contract signing and a larger one at closing — the combined deductible amount for that person is still capped at $25 for the year, not $25 per gift.
- It applies directly or indirectly. The IRS language is written broadly enough to cover gifts routed through a third party to the same end recipient, not just gifts handed over in person.
- The overage isn't deductible anywhere else. If a closing gift costs $80, you don't get to deduct the remaining $55 as a "marketing expense" or an "other expense" just by relabeling it. The IRS gift rule governs the character of the expense, not just its label.
This limit is set in the tax code itself and is not adjusted for inflation year to year. Current IRS guidance (Publication 463 for the 2025 tax year, the most recently published edition as of this writing, and the IRS's own FAQ page) confirms the figure at $25, and current professional tax commentary for 2026 continues to reference the same unchanged limit. If that ever changes, it would be a notable enough shift that it would show up across IRS guidance broadly — it isn't something that quietly moves each year the way mileage rates do.
What Doesn't Count Toward the $25 (and What Does)
The IRS carves out a few narrow exceptions that keep the $25 limit from being more punishing than it looks:
Incidental costs don't count against the limit — if they don't add substantial value. Engraving a pen, gift-wrapping a package, or paying for insurance or mailing/shipping on a gift are treated as incidental. Per IRS guidance, these costs don't reduce your deductible amount or get counted toward the $25 cap, as long as they don't meaningfully increase what the gift is worth. A $5 gift-wrapping charge on a $25 item doesn't push you over the limit; a $50 custom engraving on a $200 watch almost certainly would, because that's adding real value, not just incidental presentation.
Low-cost branded items are excluded entirely. Items that cost $4 or less, have your business name permanently imprinted on them, and are one of a number of identical items you distribute widely (think branded pens, notepads, or magnets handed out broadly) fall outside the gift rules altogether and aren't subject to the $25 cap.
Signs, display racks, and other promotional materials given to a business for use on its premises are also treated separately from the gift rules.
What this means practically: a $12 branded notepad you hand out at open houses isn't a "gift" in the IRS sense at all. A $60 bottle of wine with a card at closing is a gift, and only $25 of it is deductible.
One area to be careful with: gifts that shade into entertainment — like event tickets or a dinner — can be treated differently than a straightforward physical gift under IRS rules, and the distinction isn't always intuitive. If you're combining a gift with an experience (concert tickets, a spa day, tickets to a game), it's worth a specific conversation with your CPA about how that particular item should be characterized, rather than assuming the $25 gift rule automatically applies.
How to Track Closing Gifts So the Deduction Doesn't Get Lost
The $25 limit isn't hard to comply with — it's hard to remember to comply with, especially across a full year of closings. A few practices make it manageable:
- Log the actual cost of each gift, not just that a gift was given. You need the real receipt amount to know how much of it you're allowed to deduct, and to document that you're claiming $25 rather than the full price.
- Track gifts by recipient, not just by transaction. If the same past client, referral partner, or repeat buyer receives more than one gift from you in a year, you need to see that pattern to apply the $25 cap correctly instead of deducting $25 for each individual gift to the same person.
- Keep gifts in their own expense category, separate from general marketing or client-appreciation spending. Lumping a $150 closing gift in with "marketing" makes it easy to accidentally claim the full amount instead of the capped $25 — and makes it harder for your CPA to spot the adjustment when they prepare your return.
- Note the recipient's name on the receipt or in your bookkeeping system when you log the expense. At tax time, you or your CPA need to be able to answer "how much did this person receive from me this year," not just "how much did I spend on gifts total."
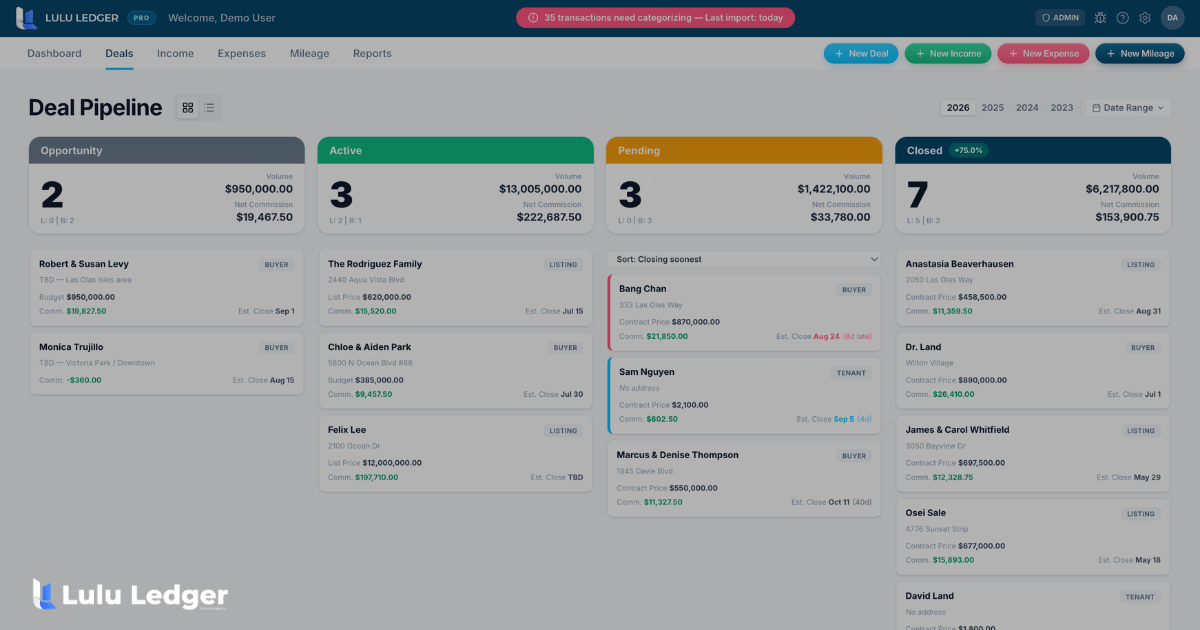
This is exactly the kind of detail that's easy to lose in a shoebox of receipts or a single "misc" spreadsheet column, and it's part of why deal-level, recipient-aware expense tracking matters more for real estate agents than it does for a business with a handful of vendor relationships. A tool like Lulu Ledger, built around how agents actually track deals, expenses, and receipts, can help you tag and total gifts by recipient throughout the year so the $25-per-person math is something you can hand your CPA cleanly, instead of reconstructing it every April.
The $25 rule isn't the hard part. Remembering who already got a gift this year, three months later, is the hard part — and that's a tracking problem, not a tax problem.
— Scott Morreau, Realtor & Founder, Lulu Ledger
None of this replaces a CPA's judgment on your specific return — especially for edge cases like gifts that double as entertainment, or gifts given jointly by a team. Lulu Ledger is a recordkeeping and planning tool; it doesn't provide tax advice or file returns, and the deduction itself is ultimately a decision for you and your tax preparer based on your full set of facts.
If you want your gift spending tagged by recipient and totalled before tax time rather than after, Lulu Ledger offers a 14-day free trial (a payment method is required, and you won't be charged until the trial ends).
Sources & References
- IRS Publication 463 (2025), Travel, Gift, and Car Expenses — "Gifts" chapter, $25 limit, incidental costs, and exceptions for low-cost branded items. irs.gov/publications/p463
- IRS.gov, Small Business/Self-Employed FAQ, "Income & Expenses 8" — confirms the $25-per-person business gift deduction limit and the incidental-cost exception. irs.gov/faqs/small-business-self-employed-other-business/income-expenses/income-expenses-8
- Current professional tax commentary (2025–2026), used for corroboration only, confirming the $25 limit remains unchanged and is not inflation-indexed.
This article is educational information, not tax, legal, or accounting advice. Confirm how these rules apply to your specific situation with a qualified CPA or tax professional.
Can I deduct the full cost of an expensive closing gift if it's a big year?
No. The $25 limit applies per recipient, per tax year, regardless of how much you actually spend or how good your production year was. A $300 gift still only yields a $25 deduction under the business gift rules.
What if I give a client a gift card instead of a physical item?
Gift cards are generally treated as gifts for this purpose and are still subject to the $25 limit, though how cash-equivalent items are treated can vary by specific circumstances — confirm with your CPA if you're unsure how a particular gift card program should be handled.
Does the $25 limit reset per transaction, or per person for the whole year?
Per person, for the whole tax year — not per transaction and not per gift. If you gave the same person two separate gifts in one year, the combined deductible total for that person is still $25.
Are branded promotional items like pens or notepads subject to the $25 limit?
Generally no, if they cost $4 or less, have your business name permanently imprinted, and are one of many identical items you distribute widely. Items that don't meet all three conditions are typically treated as ordinary gifts subject to the $25 cap.
What about gifts I give to my team or referral partners, not buyers or sellers?
The same $25-per-person, per-year rule applies to business gifts generally, not just gifts to clients. If you're giving gifts to referral partners, past clients, or vendors, they count toward the same limit for that person.
Do I need a receipt for every closing gift to claim the deduction?
Yes. As with any business expense, you should keep documentation of what you bought, what it cost, and who received it, so you (or your CPA) can substantiate the deduction if asked.
Keep reading
Reading about it is good. Seeing yours is better.
Full product, free for 14 days. Set up in about 10 minutes.