Why Your GCI Doesn't Match What You Actually Keep
GCI measures production, not take-home pay. Here's how splits, business expenses, and self-employment tax turn commission into net profit for agents.
Quick answer
GCI (gross commission income) measures production, not take-home pay. Before you see any of it, your brokerage's split and any transaction, franchise, or E&O fees come out — and those arrangements vary by brokerage, so there's no single formula. What's left is your agent compensation, and from there you still cover ordinary and necessary business expenses before you're looking at net profit. Net profit — not GCI — is the number that tells you what you actually kept, and it's also the number self-employment tax is based on.
If you've ever pulled up your year-end GCI, felt good about the number, and then wondered why your bank account doesn't reflect it, you're not doing anything wrong. You're just looking at the wrong number. GCI is a production metric. It was never designed to tell you what you kept.
GCI is a production metric, not a paycheck
Gross commission income is the total commission generated by your closed transactions before anything is taken out. It's the number your brokerage tracks for production rankings, the number teams use to measure output, and the number that shows up on award stages. It's useful for exactly one thing: measuring how much business you did.
It was never built to answer a different question — how much of that money is actually yours to spend, save, or pay taxes on. Those are two different numbers, and treating them as the same one is where the "high GCI, no money" feeling usually starts.
Where the money goes before it's yours
Before GCI becomes your compensation, your brokerage takes its share. Depending on your brokerage and your agreement, that can include:
- Your commission split or "company dollar" — the brokerage's percentage of each transaction
- A transaction fee — sometimes flat, sometimes per deal
- Franchise fees, if your brokerage operates under a franchise brand
- E&O (errors and omissions) insurance fees, often charged per transaction or annually
How these are structured, and whether any of them show up as a separate line item versus being netted out before you're paid, depends entirely on your brokerage. Some brokerages report your full GCI on your 1099-NEC and expect you to deduct the split yourself as a business expense; others only report what they actually paid you after the split. Neither approach is universal, so the only way to know how your numbers reconcile is to compare your 1099 against your actual brokerage commission statements.
Whatever is left after your brokerage's share is your agent compensation. That's a meaningfully smaller number than GCI, and it's the number your business finances should start from — but it still isn't net profit.
What's left still isn't profit
From agent compensation, you still cover your own business expenses. The IRS standard for what counts is that an expense has to be "an ordinary and necessary expense in carrying on your trade or business" (IRS Schedule C instructions). For most agents, that includes categories that map directly to Schedule C line items:
- Advertising and marketing (yard signs, digital ads, listing photography)
- Car and truck expenses, typically tracked through mileage
- Commissions and fees paid to other agents (referral fees, for example)
- Contract labor (transaction coordinators, virtual assistants)
- Insurance (E&O, if not already netted out by your brokerage)
- Legal and professional services (your CPA, an attorney)
- Office expenses and supplies
- Travel
- Business use of your home, if you qualify
None of this is a fixed percentage. A heavy marketing spend one quarter, a slow closing month, or a run of referral fees can all change what's left over — which is exactly why the number needs to be tracked deal by deal and month by month rather than estimated once a year.
Subtract these expenses from your agent compensation and you get net profit. That's the number that reflects what your business actually earned, and it's the number that determines two things that matter a lot more than GCI: your tax liability and your real cash flow.
Net profit is what you're taxed on — and it's not the same as cash in the bank
Self-employment tax — 15.3%, covering Social Security and Medicare — is calculated on your net earnings from self-employment, not on your GCI and not on your gross commission checks (IRS, Self-Employment Tax). If you're mentally reserving for taxes based on your GCI, you're either setting aside far more than you need to or, more dangerously, assuming a number that doesn't account for a slow month where expenses ate into a smaller commission.
Your bank balance on any given day is a cash flow snapshot, not a profit statement. You need to look at both.
— Scott Morreau, Realtor & Founder, Lulu Ledger
Net profit and "money in the bank" aren't the same thing either. A commission deposit can hit your account weeks after the transaction technically closed. A big expense — a marketing push, a conference, contract labor for a busy stretch — can hit before the deals it supports have closed. None of this is a reason to panic; it's just why those two numbers rarely agree in a given month.
How to actually see this number
Most of the confusion here isn't about understanding the concept — agents get it once it's explained. It's that GCI is the number that's easy to see (your brokerage hands it to you) and net profit is the number that takes work to calculate, because it means connecting every deal's commission to that deal's split, fees, and expenses, plus everything else you spent that month that wasn't tied to one transaction.
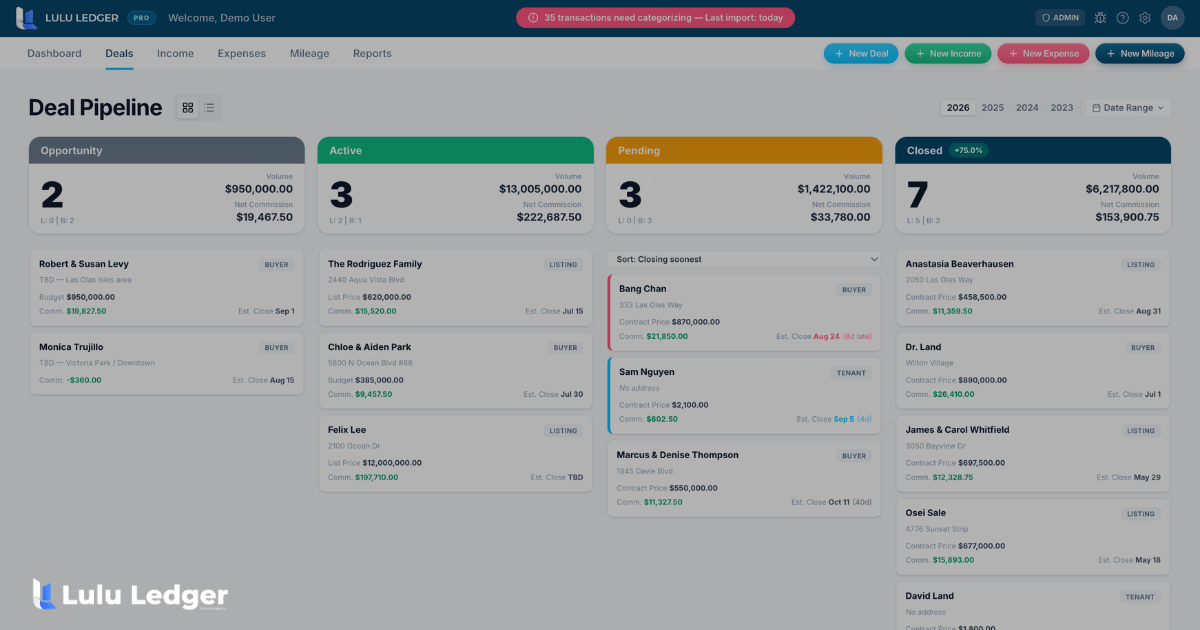
That's the gap Lulu Ledger is built to close. It connects each deal — the commission, the split, the fees — to your income and expenses, and its reports show your P&L and net profit alongside your GCI, not instead of it. So instead of finding out at tax time that a great production year didn't translate into a great year of take-home pay, you can see it as it happens.
If you want to see where your own numbers land, Lulu Ledger offers a 14-day free trial (a payment method is required, and you won't be charged until the trial ends).
Sources / References
- IRS, Instructions for Schedule C (Form 1040) — "ordinary and necessary" expense standard and Schedule C expense line categories: https://www.irs.gov/instructions/i1040sc
- IRS, Self-Employment Tax (Social Security and Medicare Taxes) — 15.3% self-employment tax rate (12.4% Social Security + 2.9% Medicare) calculated on net earnings from self-employment: https://www.irs.gov/businesses/small-businesses-self-employed/self-employment-tax-social-security-and-medicare-taxes
- NAR, "IRS Requires Reporting of Cooperative Commissions" — background on variation in how brokerages handle 1099 reporting of commissions: https://www.nar.realtor/legal/irs-requires-reporting-of-cooperative-commissions
- Lulu Ledger product pages (verified live during this run, September 21, 2026): https://lululedger.com and https://lululedger.com/pricing
About Scott Morreau
Scott Morreau is a real estate professional and the founder of Lulu Ledger, bookkeeping software built specifically for real estate agents. He built Lulu Ledger to solve his own frustration with reconciling commissions, splits, and expenses across deals, and he writes about the financial side of running an agent's business — the part that doesn't show up on a production leaderboard.
This article is for general educational purposes and isn't tax, accounting, or legal advice. Brokerage commission and 1099 reporting practices vary, and your specific tax situation depends on your facts and circumstances. Talk to your CPA or tax preparer about how these concepts apply to you.
Is GCI the same as my income?
No. GCI is the gross commission generated by your closed deals before your brokerage's split, fees, and your own business expenses come out. Your actual income — what you're taxed on and what's left to spend or save — is your net profit after all of that.
Does my brokerage's commission split count as a business expense I can deduct?
That depends on how your brokerage reports it. Some brokerages report your full pre-split GCI on your 1099-NEC, in which case the split is typically deducted as a business expense to arrive at your taxable income; others only report the amount they actually paid you after the split, in which case there's nothing left to deduct. Compare your 1099 to your brokerage commission statements, and talk to your CPA if it's not clear which applies to you.
How much of my commission should I expect to keep after expenses?
There's no universal percentage — it depends on your brokerage's split structure, your marketing spend, whether you use referral partners, and your other business costs, all of which vary widely from agent to agent and month to month. The only reliable way to know your number is to track it, not estimate it.
Do I pay self-employment tax on my GCI or my net profit?
Self-employment tax is calculated on your net earnings from self-employment — essentially your net profit after business expenses — not on your gross commission income (IRS, Self-Employment Tax).
What's the difference between net profit and the cash sitting in my bank account?
Net profit is an accounting measure of what your business earned in a period, after expenses. Your bank balance reflects timing — when deposits actually landed and when expenses were actually paid — which can differ from your profit in either direction depending on the month. Tracking both gives you the full picture; tracking only one will eventually surprise you.
How can I see my net profit instead of just my GCI?
You need your commission, brokerage fees, and business expenses connected at the deal level and rolled up over time, typically through a P&L report. Lulu Ledger builds this from your deals, income, and expenses automatically so you can see net profit alongside GCI rather than reconstructing it manually at tax time.
Keep reading
Reading about it is good. Seeing yours is better.
Full product, free for 14 days. Set up in about 10 minutes.