Real Estate Agent Mileage in 2026: The July 1 Rate Change and What Your Log Needs
The IRS standard mileage rate changed on July 1, 2026. Here's how agents split the year, what counts as business driving, and what a mileage log needs.
Quick answer
For 2026, the IRS has two business standard mileage rates: 72.5 cents per mile for expenses paid or incurred before July 1, and 76 cents per mile on or after July 1. You apply each rate to the business miles driven in its own period, so every trip in your log needs a date. Drives between your home and a regular place of work are commuting, which the IRS says you can't deduct, and whether a given drive is business or commuting depends on your facts. A usable log records the date, miles, place, and business purpose of each trip.
The 2026 mileage rate is two rates, not one
The IRS set the 2026 business standard mileage rate at 72.5 cents per mile in Notice 2026-10. In Announcement 2026-11, it raised the business rate to 76 cents per mile for expenses paid or incurred on or after July 1, 2026, and said the Notice 2026-10 rates continue to apply to expenses paid or incurred before that date. Using the standard mileage rate is optional. You can instead deduct actual vehicle costs.
If you use the standard rate, your 2026 vehicle deduction is a two-part calculation. Here's a hypothetical example, for arithmetic only. Assume an agent drove 4,000 business miles from January through June and 5,000 business miles from July through December, that the standard mileage method is available for the vehicle, that every one of those miles was deductible business driving, and that there were no parking fees or tolls.
- January through June: 4,000 miles × $0.725 = $2,900.00
- July through December: 5,000 miles × $0.76 = $3,800.00
- Total: $6,700.00
Applying one rate to all 9,000 miles would give a different answer ($6,525.00 at 72.5 cents or $6,840.00 at 76 cents), and neither matches how the IRS set the rates. That's the practical reason dates matter. A single "miles driven this year" number can't be split after the fact.
A few rules travel with the standard rate:
- It replaces separate vehicle costs. The IRS says the business standard mileage rate covers depreciation or lease payments, maintenance and repairs, tires, gasoline, oil, insurance, and license and registration fees. If you use it, you don't also deduct gas.
- Parking and tolls are separate. The IRS says business parking fees and tolls are separately deductible whether you use the standard rate or actual expenses.
- The first year matters. For a car you own, you must choose the standard mileage rate in the first year the car is available for use in your business.
- There's a vehicle-count limit. The Schedule C instructions say actual expenses are required if you operated five or more vehicles at the same time in your business.
Whether the standard rate or actual expenses works out better is a tax-preparer question, because it depends on the vehicle and your history with it.
Which drives are business, and which are commuting
The IRS draws a line in Publication 463. It says you can't deduct the cost of driving a car between your home and your main or regular place of work. It also describes situations where daily transportation is deductible:
- If you work at two places in one day, you can deduct the expense of getting from one workplace to the other.
- If you have an office in your home that qualifies as a principal place of business, you can deduct daily transportation between your home and another work location in the same trade or business.
- If you have one or more regular work locations away from home and travel to a temporary work location in the same trade or business, you can deduct the daily round trip between your home and the temporary location, regardless of distance.
The home office test is where agents get tripped up. Under Publication 587, a home office qualifies as a principal place of business when you use a specific part of your home regularly and exclusively for administrative or management activities of your business and have no other fixed location where you do substantial administrative or management work. Whether that describes you depends on where you actually handle contracts, scheduling, and bookkeeping, including whether you also keep a desk at your brokerage.
No blog post and no bookkeeping tool can tell you which side of the line your drives fall on. That's a conversation for your tax professional. What you can do is keep records that let them make the call: log each drive that might be business, with where it started and ended, so the classification can happen later from accurate data. The 2025 Schedule C instructions ask for business miles, commuting miles, and other miles, so a log that captures only the trips you've already decided are deductible leaves gaps.
What a mileage log needs to show
The IRS requires you to substantiate vehicle expenses with adequate records or with sufficient evidence supporting your own statement. For automobiles, the regulation under Internal Revenue Code section 274(d) names the elements: the amount of business use (mileage), the date, and the business purpose. IRS guidance on the standard mileage rate describes the same elements as time, place (or use), and business purpose. Publication 463 says a log, diary, notebook, or other written record can serve as your record.
On timing, the regulation says a record made at or near the time of the use, supported by sufficient documentary evidence, has a high degree of credibility that a statement prepared afterward doesn't. The same regulation allows an adequate record for part of the year to support the whole year, but only if you can show the recorded period is representative of the year's use.
A practical habit that follows from this: log trips the day they happen, or at least weekly, rather than rebuilding a year from your calendar in March. A weekly ten-minute pass is easier than reconstructing a spring and summer of showings, and it keeps the January–June and July–December split clean.
Keeping the log inside your books
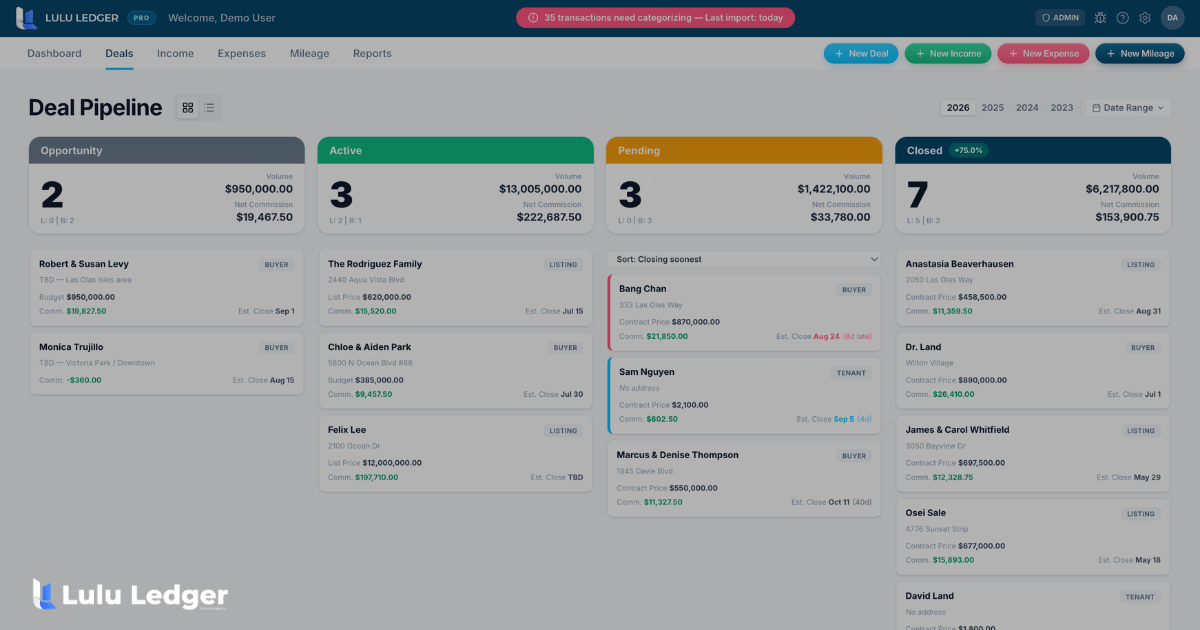
In Lulu Ledger, you log a trip with the date, miles, where it started and ended, and the purpose. Lulu Ledger records your business miles and calculates the applicable mileage amount based on the trip date, and it saves the rate with each record, so a trip in May and a trip in September are each calculated with the rate for their own date. The mileage deduction shows up as its own line in your Profit & Loss report, and you can export your mileage records as a CSV file to hand to your tax professional.
Lulu Ledger doesn't decide whether a trip is deductible or file your return. It's a recordkeeping and planning tool, so the commuting-versus-business call stays with you and your CPA. What it removes is the spreadsheet formula you'd otherwise have to remember to change on July 1.
If you want to see how the mileage log, receipts, and deals fit together, you can start free for 14 days or look at the mileage and reports features first.
Sources and references
- IRS, Standard mileage rates
- IRS, Notice 2026-10, 2026 Standard Mileage Rates
- IRS, Announcement 2026-11, Optional Standard Mileage Rates (Internal Revenue Bulletin 2026-29)
- IRS, Rev. Proc. 2019-46
- IRS, Publication 463, Travel, Gift, and Car Expenses
- IRS, Publication 587, Business Use of Your Home
- IRS, Topic no. 510, Business use of car
- IRS, Instructions for Schedule C (Form 1040), 2025
- 26 CFR 1.274-5T, Substantiation requirements
Lulu Ledger is a recordkeeping and planning tool. It does not provide tax, legal, accounting, financial, or investment advice. Review your situation with a qualified professional.
What is the IRS mileage rate for real estate agents in 2026?
The IRS business standard mileage rate is 72.5 cents per mile for expenses paid or incurred before July 1, 2026, and 76 cents per mile on or after July 1, 2026. The rate is the same for every taxpayer, so there is no separate rate for real estate agents. Using the standard mileage rate is optional; you can deduct actual vehicle costs instead.
Does the 76-cent rate apply to all of my 2026 miles?
No. The IRS says the 76-cent rate applies to expenses paid or incurred on or after July 1, 2026, and that the 72.5-cent rate from Notice 2026-10 continues to apply to expenses before that date. If you use the standard mileage rate, you calculate January through June miles at 72.5 cents and July through December miles at 76 cents.
Can I deduct gas if I use the standard mileage rate?
No. The IRS says the business standard mileage rate covers depreciation or lease payments, maintenance and repairs, tires, gasoline, oil, insurance, and license and registration fees. Business parking fees and tolls are the exception: the IRS says they are separately deductible whether you use the standard rate or actual expenses.
Is driving from my home to my brokerage office deductible?
Publication 463 says you can't deduct the cost of driving between your home and your main or regular place of work. It also says that if your home office qualifies as your principal place of business, you can deduct daily transportation between your home and another work location in the same trade or business. Which rule fits depends on your facts, so confirm with your tax professional.
Do I need a mileage log, or can I estimate my miles?
The IRS requires you to substantiate vehicle expenses with adequate records or with sufficient evidence supporting your own statement. For automobiles, the elements are the amount of business use (mileage), the date, and the business purpose. The regulation says a record made at or near the time of the trip carries a high degree of credibility that a later statement doesn't, so a log kept as you go is the safer habit.
Keep reading
Reading about it is good. Seeing yours is better.
Full product, free for 14 days. Set up in about 10 minutes.